Investors
What's the Difference Between Buying to Live in Port Stanley and Buying for Rental Income?
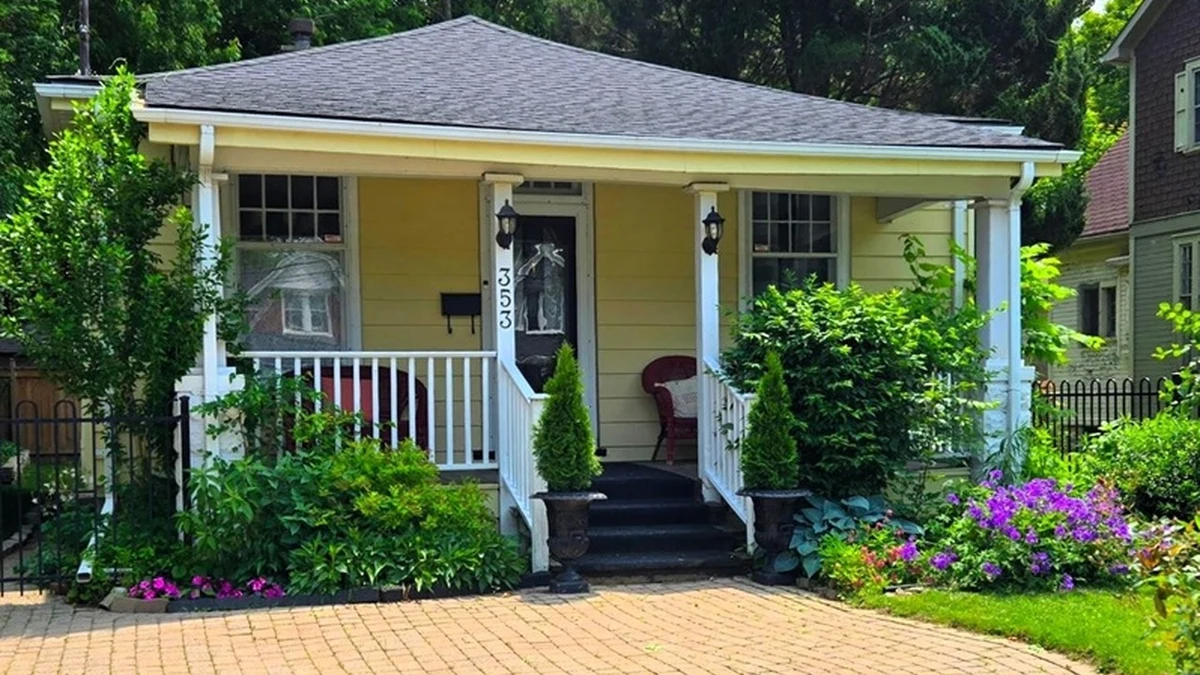
Buying a Port Stanley home to live in and buying one for rental income involve different priorities, from financing to property condition to how you evaluate location.
On this page
- Two different buyers, two different questions
- What changes when you are buying to live in it
- What changes when you are buying for rental income
- Location criteria shift depending on your goal
- Some buyers genuinely want both
- Compare the two paths side by side
- Neither path promises a specific outcome
- Starting with the right question
Two different buyers, two different questions
Someone buying a Port Stanley home to live in and someone buying a Port Stanley property for rental income are answering two different core questions, even when they are looking at similar listings.
A primary-residence buyer is mostly asking, will this work for my life. An income-property buyer is mostly asking, will this work for a tenant or renter, and does the math support it.
Keeping those questions separate, even if you are open to either path, tends to produce a clearer search.
What changes when you are buying to live in it
A primary residence search weighs personal fit heavily: commute, daily routine, how the layout suits your own life, and whether the neighbourhood feels right to you specifically.
Financing for a primary residence is usually the more straightforward path, since lenders are evaluating your own income and creditworthiness rather than projected rental income.
I had the pleasure of working with Susan as a buyer and a seller.
What changes when you are buying for rental income
An income-property search weighs different factors: what a renter or tenant is likely to want, how the property performs across a season or a year, and what the numbers actually support.
Financing gets more complex here. Lenders may treat rental income differently depending on whether it is long-term or seasonal, and documentation requirements can be more involved.
Property condition matters differently too. A primary-residence buyer might tolerate a cosmetic project; an income property may need to be tenant-ready sooner to start generating return.
Location criteria shift depending on your goal
A primary-residence buyer often weighs personal preference heavily: which street, which view, which specific feel of a neighbourhood matters to them.
An income-property buyer should weigh what a broader pool of renters wants, which may not match personal preference exactly, especially for seasonal rental demand near the shoreline.
Some buyers genuinely want both
Plenty of buyers are not choosing one path exclusively. A property used personally part of the year and rented the rest is a real, common structure in Port Stanley.
- Decide which months are yours before you buy, not after
- Confirm the property can reasonably serve both purposes without major compromises
- Ask your lender how they treat a mixed-use property upfront
- Be realistic about the management effort a mixed-use arrangement adds
A mixed-use plan can work well, but it works best when it is planned deliberately rather than discovered after closing.
Compare the two paths side by side
Putting the two approaches next to each other tends to clarify which one, or which blend, actually fits your situation.
| Factor | Buying to live in it | Buying for rental income |
|---|---|---|
| Primary question | Does this fit my life | Does this fit a renter, and do the numbers work |
| Financing path | Usually more straightforward | May require more documentation |
| Location weighting | Personal preference | Broader renter or tenant appeal |
| Condition tolerance | Can allow for a personal project | Often needs to be tenant-ready sooner |
| Flexibility | Lower, tied to your own life | Higher, tied to lease terms and season |
If you are genuinely unsure which column describes your situation, that uncertainty is worth naming directly in a first conversation rather than guessing.
Neither path promises a specific outcome
Whether you are buying to live in a property or buying it for rental income, no listing ask or informal income estimate is a guarantee of future value or return.
Bring financing, tax, and investment-analysis questions to a lender and financial advisor rather than treating website copy as that analysis.
Starting with the right question
If you are trying to decide between buying to live in Port Stanley and buying for rental income, or some deliberate mix of both, that is exactly the kind of question worth bringing to a first conversation.
Susan E. Tanton can help you think through the property side of that decision across Port Stanley, Central Elgin, and nearby Elgin County communities.
This article is general information about Port Stanley and Elgin County real estate decisions. It is not legal, financial, or tax advice. Confirm current details with Susan E. Tanton or the appropriate licensed professional.
Written by